Selling gas without the right insurance? One fuel tank leak, one slip-and-fall, or one bad storm could wipe out everything you've built. Here's what every Ontario gas station owner needs to know

Dated: March 19 2026
Views: 139
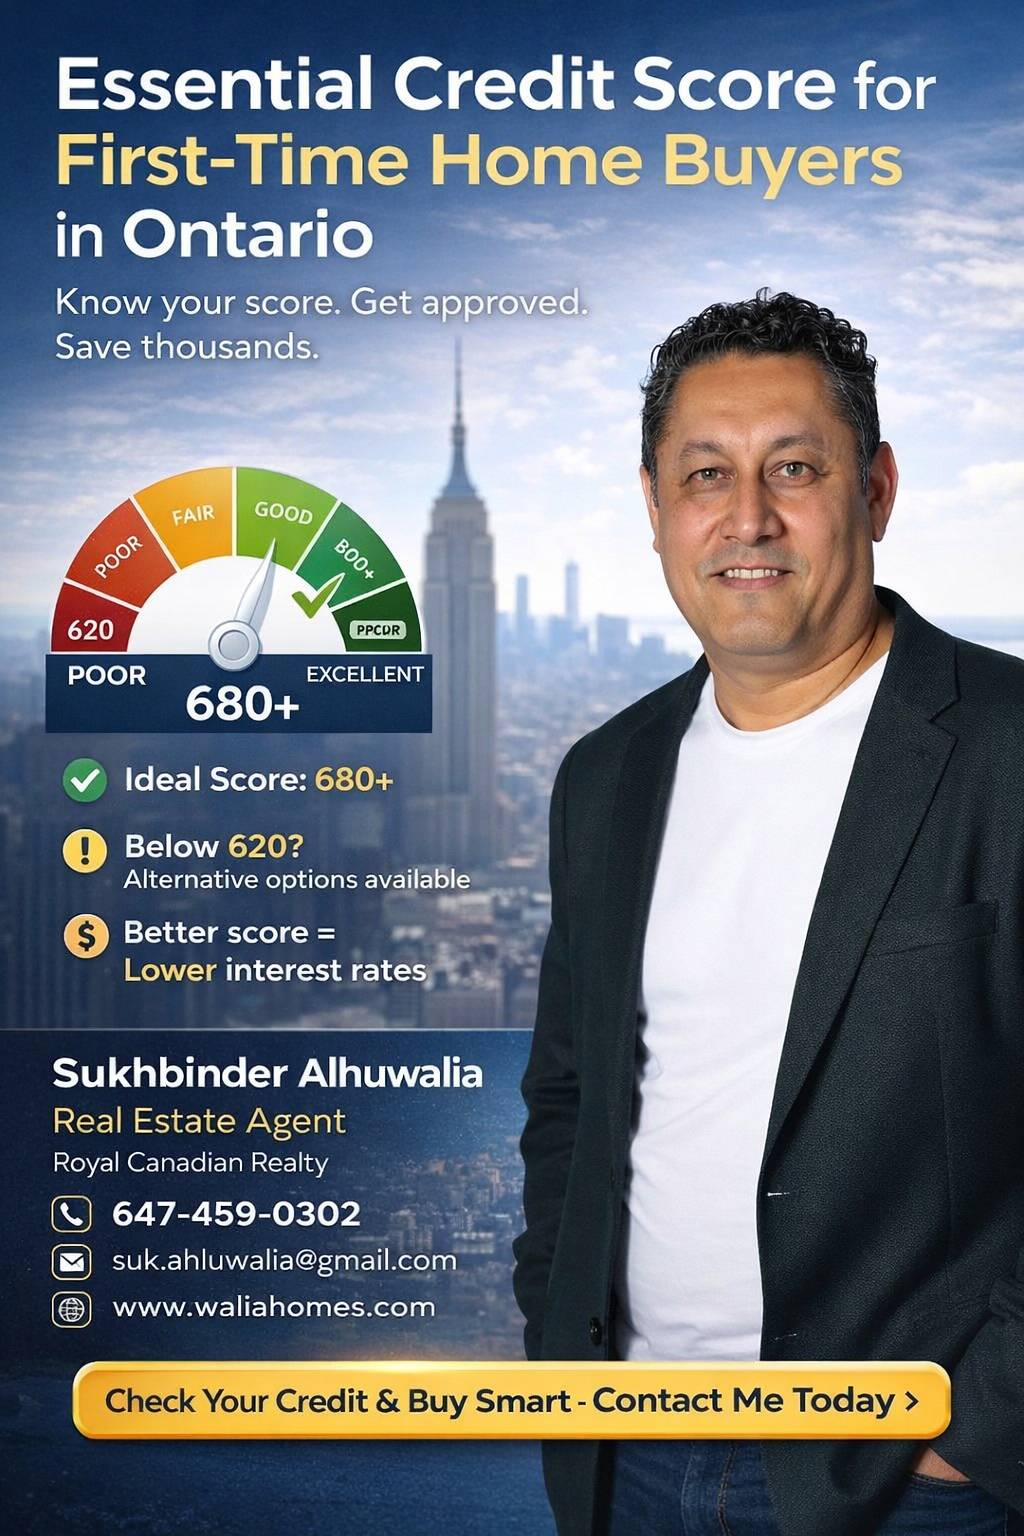
First-time buyers in Ontario—this number decides if you get approved or rejected.
Essential Credit Score for First-Time Home Buyers in Ontario
Navigating the home buying journey in Ontario? Understanding your credit score is essential for first-time buyers. Let’s demystify what you need to know.
Essential Credit Score for First-Time Home Buyers in Ontario
Navigating the home buying journey in Ontario? Understanding your credit score is essential for first-time buyers. Let’s demystify what you need to know.
Understanding Credit Scores: What You Need to Know
A credit score is a numerical representation of your creditworthiness, calculated based on your credit history. In Canada, credit scores range from 300 to 900, with higher scores indicating better credit health. This score is derived from several factors including your payment history, amounts owed, length of credit history, new credit, and types of credit used. Each of these components plays a pivotal role in shaping your overall score, which is crucial when you're planning to make significant financial decisions such as buying a home.
Payment history, which accounts for about 35% of your credit score, is the most influential factor. It reflects your track record of making payments on time. Even a single missed payment can have a negative impact, especially if it's recent. The amounts owed, comprising 30% of your score, refer to the total debt you have relative to your credit limits. High balances can indicate over-reliance on credit, which might be a red flag for lenders. The length of your credit history, which makes up 15%, looks at how long your accounts have been open. A longer credit history generally boosts your score, provided you've managed it responsibly.
New credit and the types of credit used each contribute 10% to your score. Opening several new credit accounts in a short period can suggest financial instability, while a diverse mix of credit types (such as credit cards, retail accounts, and installment loans) can positively affect your score. Understanding these factors is the first step in managing your credit score effectively, especially if you're eyeing homeownership in Ontario.
Importance of Credit Scores for Home Buying
Your credit score is a critical component when it comes to buying a home. It not only affects your ability to secure a mortgage but also influences the terms and conditions of your loan. Lenders use your credit score to gauge the risk associated with lending you money. A higher score suggests that you're less likely to default on your loan, making you a more attractive candidate for a mortgage. Consequently, you may qualify for better interest rates and more favorable loan terms, saving you thousands of dollars over the life of the loan.
For first-time home buyers in Ontario, having a good credit score can be the difference between getting approved for a mortgage and facing rejection. Given the significant investment involved in purchasing a home, lenders are particularly cautious about who they extend credit to. A poor credit score can result in higher interest rates, which means higher monthly payments and more money spent on interest over time. In some cases, it could even lead to a denial of your mortgage application, forcing you to delay your homeownership dreams.
Moreover, your credit score can affect other aspects of the home buying process. For instance, it can influence your ability to secure a favorable homeowners insurance policy, as insurers often consider credit scores when determining premiums. A lower score might result in higher insurance costs, adding to the overall expense of owning a home. Therefore, understanding the importance of your credit score and taking steps to improve it can significantly enhance your chances of a smooth and successful home buying experience in Ontario.
Ideal Credit Score Range for First-Time Home Buyers
When it comes to buying a home in Ontario, having a solid credit score can open up a world of opportunities. Generally, a credit score of 680 or higher is considered good and can help you qualify for a mortgage with favorable terms. Lenders view applicants within this range as low-risk borrowers, which can result in lower interest rates and better loan conditions. If your score is between 740 and 799, you're in excellent territory, and anything above 800 is considered exceptional, often securing the best possible rates and terms.
For first-time home buyers, aiming for a credit score of at least 680 should be a priority. This score range is typically required to access conventional mortgage loans, which are not insured or guaranteed by the government. Conventional loans often come with more flexible terms and lower interest rates compared to other types of mortgages. If your score falls below this threshold, you may still qualify for a mortgage, but the terms might not be as favorable. Scores between 620 and 679 are generally considered fair, and while you can still obtain a mortgage, you might face higher interest rates and stricter lending requirements.
If your credit score is below 620, you'll likely need to consider alternative mortgage options, such as those offered by the Canada Mortgage and Housing Corporation (CMHC). These loans are designed to help individuals with lower credit scores or limited credit history. However, they often come with higher interest rates and additional insurance premiums, which can increase the overall cost of your mortgage. Therefore, striving to improve your credit score before applying for a mortgage can significantly enhance your chances of securing a loan with favorable terms.
How Credit Scores Impact Mortgage Rates
Your credit score directly impacts the interest rates you're offered when applying for a mortgage. Lenders use your score to assess the level of risk you pose as a borrower. A higher credit score indicates a lower risk, which translates to lower interest rates. Conversely, a lower credit score suggests higher risk, leading to higher interest rates. This difference in rates can have a substantial effect on the total cost of your mortgage over time.
For example, let's consider two home buyers, one with a credit score of 750 and another with a score of 650. The buyer with the higher score might qualify for an interest rate of 2.5%, while the buyer with the lower score could be offered a rate of 4%. While this difference might seem small, it can significantly impact the total amount paid over the life of a 25-year mortgage. The buyer with the higher score would pay significantly less in interest, potentially saving tens of thousands of dollars.
In addition to the interest rate, your credit score can also affect the type of mortgage you qualify for. Lenders may offer more flexible loan terms to borrowers with higher credit scores, such as lower down payment requirements or the ability to finance closing costs. On the other hand, borrowers with lower scores might be required to put down a larger down payment or pay higher fees. Understanding how your credit score impacts mortgage rates and terms can help you make informed decisions and potentially save a significant amount of money over the life of your loan.
Steps to Improve Your Credit Score Before Buying
Improving your credit score before buying a home is a strategic move that can save you money and open up better mortgage options. The first step is to check your credit report for any errors or inaccuracies. Mistakes on your report, such as incorrect account information or fraudulent activity, can negatively impact your score. You can obtain a free copy of your credit report from the major credit bureaus and dispute any errors you find.
Next, focus on paying down existing debt. High balances on your credit cards or other loans can drag down your credit score. Aim to reduce your credit card balances to less than 30% of your credit limit. This demonstrates responsible credit use and can boost your score. Additionally, make sure to pay all your bills on time, as payment history is the most significant factor in your credit score. Setting up automatic payments or reminders can help ensure you never miss a due date.
Another effective strategy is to avoid opening new credit accounts in the months leading up to your mortgage application. Each application for credit results in a hard inquiry on your report, which can temporarily lower your score. Instead, work on managing your existing accounts responsibly. If you have limited credit history, consider becoming an authorized user on a family member's credit card or taking out a small loan to build your credit profile. By taking these steps, you can improve your credit score and increase your chances of securing a favorable mortgage.
Common Myths About Credit Scores and Home Buying
There are several myths about credit scores and home buying that can mislead potential buyers. One common misconception is that checking your own credit score will lower it. In reality, checking your score yourself results in a soft inquiry, which does not affect your credit score. It's only hard inquiries, like those made by lenders during the mortgage application process, that can temporarily lower your score.
Another myth is that you need a perfect credit score to buy a home. While having a high score can certainly provide advantages, it's not a strict requirement. Many successful home buyers have scores in the fair to good range. Lenders consider various factors when assessing mortgage applications, including income, employment history, and debt-to-income ratio. Therefore, a less-than-perfect credit score doesn't automatically disqualify you from obtaining a mortgage.
A third myth is that closing old credit accounts will improve your score. In fact, closing accounts can sometimes have the opposite effect. Length of credit history is a factor in your credit score, and closing older accounts can shorten your overall credit history, potentially lowering your score. Additionally, closing accounts reduces your available credit, which can increase your credit utilization ratio. It's generally better to keep old accounts open, especially if they have a positive payment history. Understanding these myths can help you make informed decisions and avoid common pitfalls in your home buying journey.
Resources for Checking and Monitoring Your Credit Score
Staying on top of your credit score is crucial, especially when you're planning to buy a home. There are several resources available to help you check and monitor your credit score. In Canada, the two main credit bureaus are Equifax and TransUnion. Both offer services that allow you to access your credit report and score. You can obtain a free copy of your credit report from each bureau once a year, which is an excellent way to ensure all the information is accurate.
In addition to the credit bureaus, there are several online tools and apps that provide credit monitoring services. Platforms like Credit Karma and Borrowell offer free access to your credit score and provide insights into the factors affecting it. These tools often include features such as credit alerts, which notify you of significant changes to your report, and personalized tips for improving your score. Regular monitoring can help you stay informed and take proactive steps to maintain or improve your credit health.
Another valuable resource is your bank or credit card issuer. Many financial institutions now offer free credit score monitoring as part of their services. This can be a convenient option, as it allows you to keep track of your score alongside your other financial accounts. By leveraging these resources, you can stay informed about your credit status and make informed decisions as you prepare for homeownership.
The Role of Lenders in Assessing Your Credit Score
Lenders play a crucial role in the home buying process, and your credit score is one of the primary factors they consider when assessing your mortgage application. When you apply for a mortgage, lenders will request a copy of your credit report from one or both of the major credit bureaus. They use this information to evaluate your creditworthiness and determine the level of risk associated with lending you money.
In addition to your credit score, lenders will examine other aspects of your credit report, such as your payment history, outstanding debts, and the types of credit you have. They will also consider your income, employment history, and debt-to-income ratio to get a comprehensive picture of your financial health. This holistic approach helps lenders assess your ability to repay the loan and make informed decisions about the terms and conditions of your mortgage.
It's important to note that different lenders may have varying criteria and thresholds for credit scores. Some lenders might be more flexible and willing to work with borrowers who have lower scores, while others may have stricter requirements. This is why it's essential to shop around and compare offers from multiple lenders. By understanding the role of lenders in assessing your credit score, you can better prepare for the mortgage application process and increase your chances of securing a favorable loan.
Alternatives for Buyers with Low Credit Scores
If you have a low credit score, don't despair. There are still options available for buying a home in Ontario. One alternative is to consider government-backed mortgage programs, such as those offered by the Canada Mortgage and Housing Corporation (CMHC). These programs are designed to help individuals with lower credit scores or limited credit history access affordable home financing. While these loans often come with higher interest rates and additional insurance premiums, they can provide a viable path to homeownership for those who might not qualify for conventional loans.
Another option is to explore lending institutions that specialize in working with borrowers with low credit scores. Some lenders, known as subprime lenders, offer mortgage products tailored to individuals with less-than-perfect credit. While these loans typically come with higher interest rates and fees, they can be a valuable resource for those who need a mortgage but don't meet the stringent requirements of traditional lenders. It's essential to carefully review the terms and conditions of any subprime loan to ensure you fully understand the costs and obligations involved.
Additionally, you might consider seeking a co-signer for your mortgage. A co-signer with a strong credit profile can help bolster your application and improve your chances of securing a loan. The co-signer agrees to take on the responsibility of repaying the mortgage if you default, which reduces the risk for the lender. However, this is a significant commitment, and it's crucial to have a clear understanding and agreement with your co-signer about the responsibilities and potential risks involved. By exploring these alternatives, you can find a path to homeownership even if your credit score is less than ideal.
Conclusion: Navigating the Home Buying Process with Confidence
Navigating the home buying process in Ontario as a first-time buyer can be both exciting and daunting. Understanding your credit score and its impact on your ability to secure a mortgage is a crucial step in this journey. By familiarizing yourself with the factors that influence your credit score, taking proactive steps to improve it, and exploring the various mortgage options available, you can position yourself for success.
Remember that a good credit score can open doors to better mortgage rates and terms, potentially saving you thousands of dollars over the life of your loan. However, even if your credit score is not where you'd like it to be, there are still options available to help you achieve your homeownership dreams. By leveraging resources for checking and monitoring your credit score, understanding the role of lenders, and considering alternatives for buyers with low credit scores, you can make informed decisions and navigate the home buying process with confidence.
Ultimately, buying a home is a significant financial milestone, and being well-informed about your credit score can make a substantial difference in your experience. With the right knowledge and preparation, you can confidently embark on your home buying journey and find the perfect home in Ontario.
· credit score Ontario · first time home buyer Canada · mortgage approval Ontario · credit score for mortgage Canada · minimum credit score Canada · home buying tips Ontario · improve credit score Canada · mortgage rates Canada · real estate Ontario · first time buyer tips · credit report Canada · CMHC mortgage Ontario · credit score 680 mortgage · home loan approval Canada
#FirstTimeHomeBuyer #OntarioRealEstate #CreditScoreCanada #MortgageTips #HomeBuyingTips #RealEstateOntario #CanadianRealEstate #MortgageAdvice #CreditScoreTips #BuyAHomeCanada #CMHC #InvestmentProperty #PreConstructionOntario #RealtorOntario #GTARealEstate #FinancialTips #HomeOwnership #RealEstateInvesting #MortgageApproval #WealthBuilding
“Not sure if your credit score is good enough to buy a home?”
📲 Call or text me at 647-459-0302 for a FREE consultation
💬 Or message me “CREDIT” and I’ll guide you step-by-step
Selling gas without the right insurance? One fuel tank leak, one slip-and-fall, or one bad storm could wipe out everything you've built. Here's what every Ontario gas station owner needs to know
Thinking about buying a gas station in Ontario? Don’t make a move until you complete proper due diligence. One missed check can cost you thousands. Essential Due Diligence for Buying a
Thinking about buying a gas station in Ontario? Don’t make a move until you understand the numbers, risks, and due diligence.Owning a gas station can be a rewarding investment&mdash
Want passive income in Ontario real estate? 💰 Multi-family properties are the #1 way investors are building cash flow in 2026.” Discover Profitable Cash Flow Multi-Family Properties in
 Toronto Real Estate Board (TRREB); All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 3:07 PM UTC
Show More...

The listing data displayed is deemed reliable but is not guaranteed accurate by CREA®. Data last updated on September 22, 2026 4:34 PM UTC The trademarks REALTOR®, REALTORS®; and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA®) and identify real estate professionals who are members of CREA®. Used under license. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA®) and identify the quality of services provided by real estate professionals who are members of CREA®. Used under license.
Show More...
 Data provided by the Ontario Regional Technology & Information Systems. The information is deemed reliable, but is not guaranteed. Not intended to solicit buyers or sellers, landlords or tenants currently under contract.
The trademarks REALTOR®, REALTORS® and the REALTOR® logo are controlled by The Canadian Real Estate Association (CREA) and identify real estate professionals who are members of CREA. The trademarks MLS®, Multiple Listing Service® and the associated logos are owned
by CREA and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.
REALTOR® contact information provided to facilitate inquiries from consumers interested in Real Estate services. Please do not contact the website owner with unsolicited commercial offers.
Show More...
 All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. The data relating
to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Royal Canadian Realty, Brokerage, Mississauga may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 9:34 AM UTC
Show More...
